Buying Property in the UK in 2026
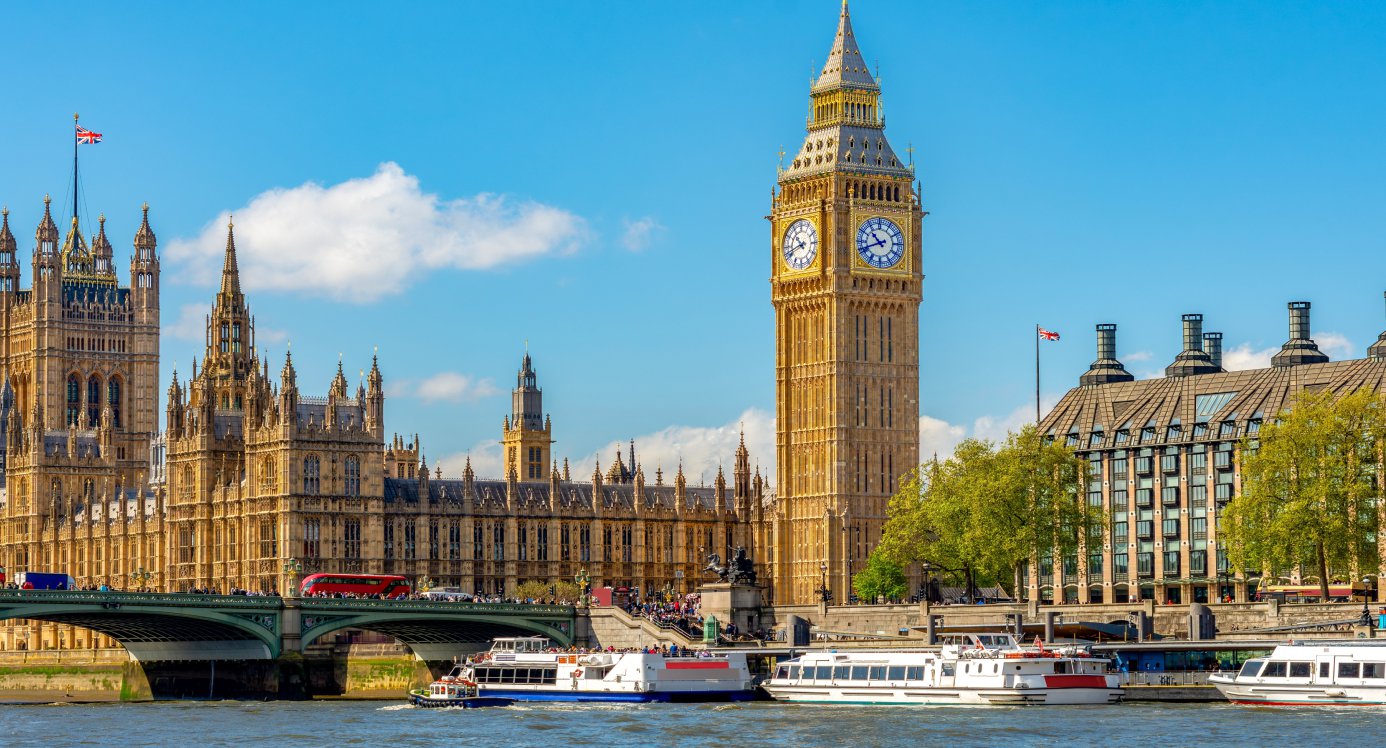
Everything you need to know about buying property in the UK: the benefits of investment, taxes, forms of ownership, and key considerations for foreign buyers. The article also highlights why London stands out as an investment location.
How to Buy Property in the UK for Foreigners
There are no legal restrictions on property purchases in the UK for non-residents. Foreign nationals have the same rights as UK residents when it comes to buying residential and commercial property. Overseas investors can purchase both completed homes and off-plan developments.
To buy property in the UK, foreign buyers must provide proof of identity and address, along with evidence of financial means. UK banks often work with international clients, especially those with stable income and a deposit of at least 25%.
Benefits of Property Investment in the UK and in London
Reasons why overseas buyers choose this location:
- A global financial hub. London is one of the world’s major business centres and ranks first for business-friendly conditions. Rental demand remains strong, particularly in central and commercial areas.
- Capital protection. The UK’s legal system offers robust protection of property rights — even for foreign investors.
- Long-term price growth. Historically, London property has appreciated steadily in value, especially in high-end areas.
- Strong rental market. A large portion of the population rents, especially students, expats, and young professionals.
- Prestige and liquidity. London real estate is considered a prestigious asset and is easily sold on the global market. Demand consistently outstrips supply.
- London is one of the most cosmopolitan cities in the world, with over 300 languages spoken and 37% of residents being foreign nationals.
- World-class education. British universities consistently rank at the top of the QS World University Rankings.
Popular London districts each have their own unique charm and historical architecture. For example, Mayfair remains a premium area due to its concentration of luxury hotels, fine dining, and headquarters of major corporations — property prices here are among the highest in London. Belgravia attracts buyers with its elegant townhouses, while Kensington stands out for its green squares and parks.

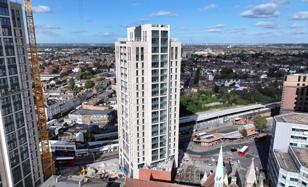 From £386,000
Built in 2023 Total of 108 apartments
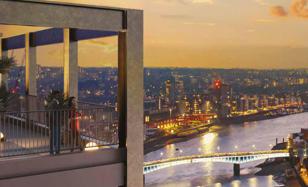 From £923,000
Completion in: 2026.II Total of 113 apartments
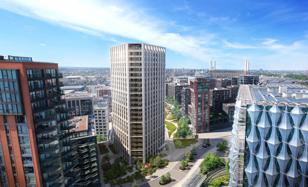 From £4,548,000
Built in 2025 Total of 186 apartments
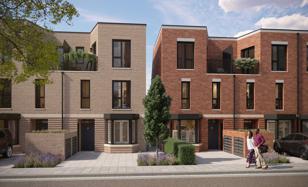 From £1,256,000
Completion in: 2027.I 30 units in total
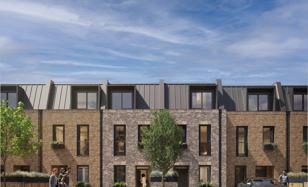 From £1,143,000
Completion in: 2027.II 57 units in total
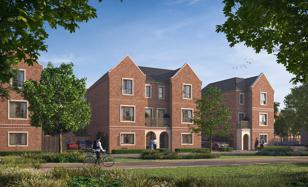 From £1,453,000
Built in 2025 145 units in total
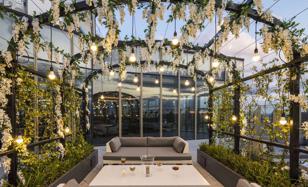 From £697,000
Built in 2019 Total of 412 apartments
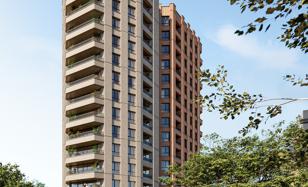 From £435,000
Completion in: 2028.I Total of 122 apartments
Property Ownership Types in the UK
Understanding ownership structures is essential when buying property in the UK. The British legal system offers several forms of tenure, each with distinct features and limitations.
Freehold — full ownership
Freehold means full ownership of both the property and the land it sits on. A freehold owner holds the title in perpetuity, with no time restrictions. This type of ownership comes with no ground rent or service charges.
Most houses in the UK are sold as freehold, offering maximum control over the land. The owner is fully responsible for the upkeep and maintenance of the property, including gardens and surrounding areas.
Leasehold — long-term lease
Leasehold gives the right to occupy a property for a fixed period — typically 90 to 999 years. Leaseholders own the building but not the land beneath it, which remains under the freeholder’s ownership.
Leaseholders must pay ground rent and service charges to a managing agent. Most flats and apartments in the UK are sold on a leasehold basis.
From £386,000
Built in 2023 Total of 108 apartments
From £923,000
Completion in: 2026.II Total of 113 apartments
From £4,548,000
Built in 2025 Total of 186 apartments
From £1,256,000
Completion in: 2027.I 30 units in total
From £1,143,000
Completion in: 2027.II 57 units in total
From £1,453,000
Built in 2025 145 units in total
From £697,000
Built in 2019 Total of 412 apartments
From £435,000
Completion in: 2028.I Total of 122 apartments
Commonhold — shared ownership
Commonhold is a relatively new form of ownership, where flat owners have full title to their individual units and jointly manage shared areas of the building through a management company.
Feature | Freehold | Leasehold |
Ownership | Full ownership of house and land | Right to occupy for lease term |
Tenure | Unlimited | 99–999 years |
Maintenance Responsibility | Fully the owner’s | As per lease agreement |
Additional Payments | None | Ground rent, service charges |
Right to Sell | No restrictions | With freeholder’s consent |
Inheritance | Unlimited transfer | Remaining lease term only |
Step-by-Step Process to Buy Property in the UK
The property purchase process in the UK consists of six key stages and typically takes 4–8 weeks in total. Each step is strictly regulated by British law and requires the involvement of qualified professionals.
Finding a Property and Making an Offer
The first step involves finding a suitable property and submitting an offer. The offer may reflect the full market value or be lower, depending on current market conditions. It’s important to note that an accepted offer is not legally binding — either party can withdraw from the transaction before the exchange of contracts.
Appointing a Solicitor and Preparing Documentation
Once the price is agreed, a solicitor (property lawyer) steps in. Legal conveyancing is a mandatory part of all UK property transactions. The buyer’s solicitor receives the draft contract from the seller’s solicitor and conducts thorough due diligence on the property and associated documents.
Independent Property Survey
A building survey is carried out by a licensed surveyor to assess the property’s structural condition, detect hidden defects, and determine its true market value. The cost of a survey typically ranges from 500 to 1,500 pounds.
Exchange of Contracts
The exchange of contracts is a critical milestone — at this point, the agreement becomes legally binding. The buyer pays a deposit, usually around 10% of the property price. After exchange, neither party can back out without financial penalties.
Completion
Completion is the final step, when full payment is made and the keys are handed over. Completion usually takes place 1–3 weeks after exchange. On the day of completion, the buyer must also pay stamp duty land tax.
Registration with the Land Registry
The last step is registering ownership with the Land Registry. The buyer’s solicitor submits the required documentation to officially record the new owner. Registration is backed by the state and is mandatory for all property transactions.
Buying property is possible for foreigners, provided you find a reliable developer and lawyer.
Speak to our expert
Documents Required to Buy Property in the UK
All documents for purchasing property in the UK must meet the country’s legal standards. The following are typically required:
- A valid passport with a certified English translation.
- Proof of address (utility bills or bank statements).
- A bank statement confirming availability of funds.
- A criminal record certificate.
- Evidence of the source of funds.
- Apostilles for any documents issued outside the UK.
- Notarised translations of all documents into English.
Property Taxes in the UK
Buying property in the UK involves several mandatory taxes, depending on the property’s price and the buyer’s status.
Stamp Duty Land Tax (SDLT)
SDLT is the main property purchase tax, calculated on a progressive scale. As of 1 April 2025, new SDLT rates have been introduced, increasing the tax burden for most buyers.
Property Value (Residential) | SDLT Rate (Residential) | Property Value (Non-Residential) | SDLT Rate (Non-Residential) |
Up to 125,000 £ (or 300,000 £ for first-time buyers) | 0% | Up to 150,000 £ (lease < 1,000 £/year) or 300,000 £ for first-time buyers | 0% |
125,001–250,000 £ | 2% | Up to 150,000 £ (lease > 1,000 £/year) | 1% |
250,001–925,000 £ | 5% | 150,001–250,000 £ | 1% |
925,001–1,500,000 £ | 10% | 250,001–500,000 £ | 3% |
Over 1,500,000 £ | 12% | Over 500,000 £ | 4% |
Additional Taxes for Non-Residents
Non-residents must pay a 2% surcharge on top of all SDLT bands. An additional 3% levy also applies to investment properties.
Capital Gains Tax (CGT) on Sale
CGT applies when non-residents sell property in the UK. The rate is 18% for basic-rate taxpayers and 24% for higher-rate taxpayers.
Mortgages in the UK for Foreigners
Mortgages are available to foreign citizens in the UK, but banks impose stricter requirements on non-residents than on local borrowers.
Mortgage Conditions for Non-Residents
Foreign buyers can apply for a UK mortgage if they meet the following conditions:
- Minimum annual income of 75,000 £ for residential purchases.
- Minimum annual income of 50,000 £ for buy-to-let properties.
- Deposit of at least 25% of the property value.
- Maximum loan-to-value (LTV) ratio of 75%.
Bank Requirements and Interest Rates
British lenders require non-residents to provide evidence of stable income and verify the source of their funds. Interest rates for non-resident mortgages are typically 0.5–1% higher than those for UK residents. For properties worth over 1 million pounds, the required deposit may rise to 40%.
Property Costs in the UK
In addition to the property’s price, buyers should expect additional costs amounting to around 3–7% of the property’s value.
Expense Type | Cost | Notes |
Legal Services (Solicitor) | 0.3% of property value | + VAT |
Independent Survey (Building Survey) | from 1,000 £ | + VAT |
Land Registry Registration | from 200 £ | Depends on property value |
Bank Transfers | 35–50 £ | Per transaction |
Property Insurance | 300 £ per year | Average UK rate |
Investing in UK Property
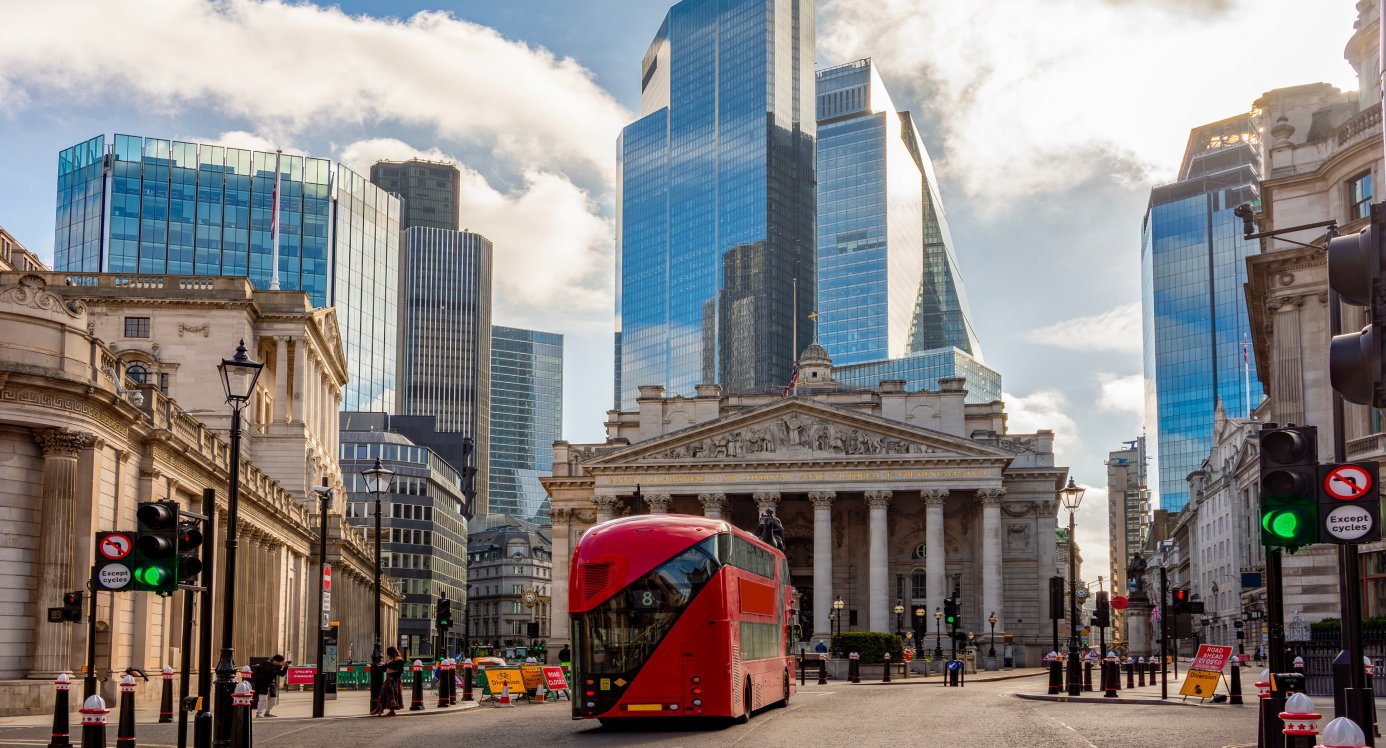
UK real estate remains a highly attractive investment, thanks to steady price growth and rental income opportunities. According to the Global Property Guide, the average rental yield in the UK is 7.03% annually.
Rental Income from Buy-to-Let Apartments
Buy-to-let flats offer a reliable stream of income via rental payments. Landlords must pay income tax on rental earnings at rates of 20%, 40%, or 45%, depending on their total annual income.
Total Income | Tax Rate |
Up to 12,570 £ | 0% |
12,571–50,270 £ | 20% |
50,271–125,140 £ | 40% |
Over 125,140 £ | 45% |
Key expenses that can be deducted from taxable income:
- Mortgage interest payments (subject to limits).
- Council Tax and building insurance.
- Maintenance and repair costs.
- Legal and management fees.
Property Tax Obligations
Owners of investment properties must account for Council Tax — a local authority tax that typically ranges from 1,200 to 2,000 pounds per year, depending on the property’s value and location.
We will send you a content digest not more than once a week
- Property Prices
- Buying and Registering
- Mortgage
- Residence
- Property Maintenance
- Taxes