Taxes in Cyprus in 2026

Cyprus stands out among most European jurisdictions due to its significantly lower tax burden. There is no property ownership tax, favourable VAT rates apply, and the Non-Domicile regime allows for the reduction of taxes on passive income to zero, among other benefits.
For private investors, Cyprus offers one of the most advantageous environments for investing in overseas property within the EU.
Property Tax in Cyprus
When purchasing property in Cyprus, investors encounter several mandatory payments, which vary depending on the type of property and the structure of the transaction.
 From 205,000 €
Completion in: 2027.II Total of 105 apartments
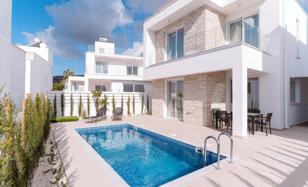 From 520,000 €
Built in 2022 64 units in total
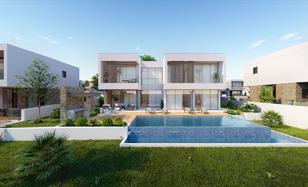 From 800,000 €
Built in 2025 67 units in total
 From 320,000 €
Completion in: 2028.IV Total of 88 apartments
 From 845,000 €
Completion in: 2027.I Total of 330 apartments
 From 545,000 €
Completion in: 2026.IV Total of 24 apartments
 From 510,000 €
Completion in: 2026.IV Total of 44 apartments

Transfer Tax in Cyprus
The transfer of ownership is registered with the Department of Lands and Surveys (DLS). The buyer is required to pay transfer fees, the rates of which depend on the market value of the property as determined by the DLS.
The tax applies to all types of property, including residential homes, apartments, commercial premises, and land plots, if purchased from another owner.
Transfer tax rates range from 3% to 8%, depending on the property value:
Property Value (€) | Tax Rate |
Up to 85,430 | 3% (max €2,550) |
85,431 — 170,860 | 5% (max €6,800) |
Over 170,860 | 8% |
Exemptions and discounts apply for transfers between family members or between family members and family-owned companies.
The DLS website provides a transfer tax calculator.
Should the tax authorities deem the declared transaction value to be significantly below market rates, they reserve the right to impose additional Transfer Tax on the difference. Properties acquired through forced sales, however, are not eligible for preferential rates.
Contracts registered with the Land Registry between 2 December 2011 and 31 December 2016 continue to benefit from reduced Transfer Tax rates, irrespective of the date when ownership is formally transferred.
When purchasing a property directly from a developer, VAT applies instead of Transfer Tax, offering a notable exemption from transfer fees.
Stamp Duty
Stamp Duty is paid on property purchase transactions, calculated based on the property’s value:
Property Value (€) | Rate (%) |
Up to 5,000 | 0.00 |
5,001 — 170,000 | 0.15 |
Over 170,000 | 0.20 |
Transactions involving company reorganisations or assets located outside Cyprus are exempt from Stamp Duty.
The maximum Stamp Duty liability is capped at €20,000.
VAT on Property Purchases
Property sales in Cyprus attract VAT if the transaction occurs before the property’s first occupation or within five years of construction completion, provided it has not been occupied by a third party for at least 24 months.
VAT is triggered upon the initial transfer of ownership for a previously unused property.
The standard VAT rate in Cyprus is 19%. However, buyers may qualify for a reduced rate of 5% under specific conditions:
- The purchase is made by an individual.
- The property will not be let out.
- It will serve as the buyer’s primary residence in Cyprus, with no other property on the island acquired under the reduced VAT rate within the past ten years.
The 5% rate applies to the first 130 square metres of a residence, capped at a value of €350,000, with the total transaction value not exceeding €475,000 and the total area not surpassing 190 square metres.
Exceptions:
- Individuals with disabilities may benefit from the 5% rate on the first 190 square metres, regardless of total area.
- The value threshold may be adjusted at the discretion of the Tax Commissioner.
Properties with planning permission applied for or granted before 31 October 2023 are ineligible for this relief.
The reduced VAT rate precludes letting the property. Should you wish to generate rental income, the difference between the 5% and 19% rates must be settled. Notably, Cyprus Permanent Residency for investment remains achievable under either VAT rate.
Reapplying the Reduced 5% VAT Rate
Previously, reapplying for the reduced rate within ten years required repayment of the difference between the standard and reduced rates for the entire ownership period. Under updated legislation, the conditions are now as follows:
- Notify the Tax Commissioner within 30 days of ceasing to use the property as a primary residence.
- Pay the VAT difference proportional to the remaining ten-year period, unless the property is transferred to children or upon the owner’s passing.
Full recovery of the 19% VAT is possible when letting a property through a management company. Contact us to explore projects with management services and VAT reclaim potential.
Request a Consultation
VAT on Land
Since 2 January 2018, the sale of undeveloped land designated for construction has been subject to 19% VAT. This applies to plots intended for one or more developments as part of a business activity. Exemptions include land in livestock zones, as well as protected natural, archaeological, or agricultural areas.
Property Ownership Taxes in Cyprus
The annual Property Tax in Cyprus was abolished on 1 January 2017. Prior to this, it was levied on owners listed in the registry as of 1 January each year, based on the property’s market value as of 1 January 1980, with rates ranging from 6% to 19%.
Healthcare Contributions
Owners earning rental income must contribute to the General Healthcare System (GESY) at a rate of 2.65% of gross income, effective since 1 March 2019. The maximum taxable income is capped at €180,000 annually, with no deductions (e.g., for maintenance) applied to the gross figure.
GESY contributions can be deducted from your income tax liability.
Capital Gains Tax (CGT)
CGT applies at 20% on profits from disposing of Cypriot property or unlisted company shares tied to Cypriot real estate (where over 50% of the company’s market value derives from such assets).
Taxable events include:
- sales;
- exchanges;
- gifting;
- sums collected on cancellation of real estate transactions;
- provision of purchase rights.
The tax is calculated on the profit — sale price minus purchase cost — adjusted for inflation and improvement expenses.
Example: An investor buys a property for €200,000 in 2010 and sells it for €300,000 in 2024. With an inflation-adjusted cost of €230,000 and €10,000 in renovation costs, the taxable profit is €60,000, resulting in a CGT liability of €12,000 (20%).
Tax Calendar for Property Owners in Cyprus
Deadline | Tax | Rate |
31 March | Corporate Income Tax (rental via entity) | 12.5% |
30 June | SDC on rent (first 6 months) | 3% |
31 July | Personal Income Tax (rental) | 0–35% |
31 December | SDC on rent (second 6 months) | 3% |
30 June & 31 December | Healthcare Contribution (6 months) | 2.65% |
Within 30 days of contract | Stamp Duty | Up to 0.20% |
Within 30 days of transaction | Capital Gains Tax | 20% |
Income Tax for Individuals
Individuals classified as tax residents of Cyprus are liable for income tax on earnings derived both within the country and globally. Typically, tax residency is established by spending more than 183 days per year in Cyprus.
Since 1 January 2017, an alternative route to tax residency has been available for those present in Cyprus for as little as 60 days annually, provided the following conditions are met:
- The individual does not reside in any other country for more than 183 days in aggregate during the same year.
- They are not a tax resident of another jurisdiction in that year.
- They spend at least 60 days in Cyprus.
- They engage in business activities, are employed, or hold a position in a Cyprus tax-resident company during the tax year.
- They maintain a permanent residence in Cyprus, whether owned or rented.
Taxes paid abroad may be offset against Cypriot income tax liabilities, supported by a double taxation treaty between Cyprus and other countries.
Personal income tax rates range from 0% to 35%, including rental income. For the 2026 tax year, the bands are:
Income (€) | Rate (%) |
Up to 22,000 | 0 |
22,001–32,000 | 20 |
32,001–42,000 | 25 |
42,001–72,000 | 30 |
Over 72,000 | 35 |
Rental income is subject to income tax. To optimise your tax position, consider letting property through a corporate entity, where the corporate tax rate is a competitive 12.5%. Contact us for further guidance on structuring your rental strategy effectively.
Contact us
Pension income from overseas is taxed at a fixed rate of 5%, with an annual tax-free allowance of €3,420. Additional reliefs and deductions may also apply.
Corporate Tax
Cyprus offers an attractive corporate tax rate of 12.5%, applicable to profits from both domestic and international sources for tax-resident companies.
Under the Intellectual Property Box regime, technology companies benefit from significant relief, with 80% of qualifying income exempt from taxation. The remaining 20% is taxed at 12.5%, reducing the effective rate to just 2.5%.
Non-resident companies are taxed on profits from permanent establishments in Cyprus and certain Cyprus-sourced income. A company is deemed tax resident if its management and control are exercised in Cyprus.
Foreign taxes paid may be credited against Cypriot corporate tax obligations.
Dividend Tax
Dividends received by Cyprus-registered companies are exempt from taxation and excluded from net profit calculations. However, individuals with «domicile» status in Cyprus face a Special Defence Contribution (SDC) of 17% on dividends.
The Non-Domicile (Non-Dom) status offers a compelling solution for tax optimisation, available for 17 years. It exempts holders from tax on passive income, including dividends, interest, and the SDC on rental income:
Income Type | Tax without Non-Dom | Tax with Non-Dom |
Dividends | 17% | 0% |
Interest | 30% | 0% |
Rent | 3% | 3% |
Navigating the intricacies of Cypriot taxation requires expert insight. Our tax specialists at Tranio can assess your case, calculate precise liabilities, and identify optimisation strategies. Request a consultation to explore how we can support your investment journey, from acquisition to ongoing management.
Request a Consultation
📊 Corporate tax at 12.5%
💼 Business tax breaks
📉 Non-Dom tax status


We will send you a content digest not more than once a week