Mortgage in Indonesia in 2026

Foreign nationals cannot hold Hak Milik freehold title, but may hold qualifying housing under Hak Pakai with valid immigration documents. Mortgage finance remains limited, although some banks offer products for KITAS or KITAP holders.
One alternative for foreign investors is instalment plans from developers. These programmes allow foreign investors to finance property purchases on more favourable terms, offering a convenient payment plan during the construction period.
From Colonial Imbalances to Citizen-Centric Policies: Real Estate Regulations in Indonesia
The policy of restricting foreign ownership of real estate and access to mortgages in Indonesia is based on historical experience, economic policies, and the commitment to protect citizens’ interests.
During the colonial era, foreign ownership of Indonesian land led to significant economic and social imbalances due to the lack of control over the land by Indonesian citizens. Following its independence in 1945, Indonesia prioritised private land ownership for its citizens as a means of addressing the imbalances that had been created during the colonial era.
Indonesian Mortgage Law
The Basic Agrarian Law (Law No. 5 of 1960) places restrictions on foreign ownership of real estate in Indonesia. In particular, it allows only Indonesian citizens and legal entities to fully own land.
Foreigners can enter into long-term land leases, but cannot directly own freehold properties.
The 1996 Mortgage Law (UU No. 4) governs Hak Tanggungan security rights. Whether a loan can be secured depends on the land right and transaction structure, which the lender and notary must check; Article 10 does not confine such lending to construction.
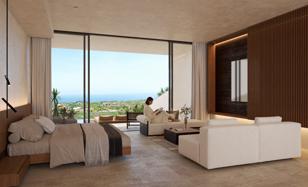 $415,000
Total area 80 m² 1 bedroom
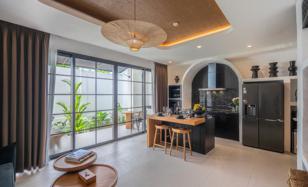 $180,000
Total area 82 m² 1 bedroom
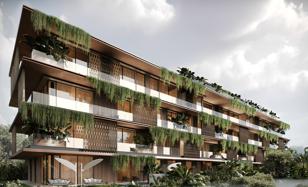 From $120,000
Yield 10.0% Completion in: 2028.IV
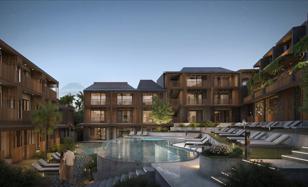 From $145,000
Yield 10.0% Completion in: 2028.I
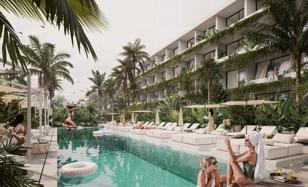 From $97,000
Yield 10.0% Built in 2026
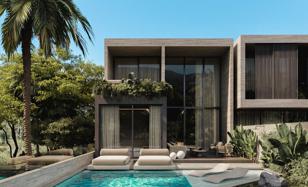 From $248,000
Yield 9.0% Completion in: 2027.III
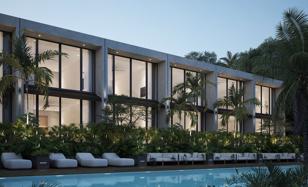 From $197,000
Yield 8.0% Built in 2026
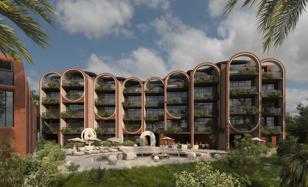 From $126,000
Yield 8.0% Completion in: 2027.II
In 2025, select banks began rolling out tailored financial products for foreign nationals.
In June 2025, Indonesia’s Permata Bank launched the country’s first dedicated mortgage program for expatriates — Permata KPR iB IMBT WNA. This initiative marks a significant step toward lowering one of the main barriers to foreign participation in the residential property market.
The product is designed for non-Indonesian citizens holding either temporary or permanent residence permits (KITAS/KITAP) and is structured in accordance with Islamic finance principles.
Key Features of the New Expatriate Mortgage in Indonesia:
- Minimum property value: IDR 2 billion (approx. $125,000)
- Minimum loan amount: IDR 1 billion ($62,500)
- Loan-to-value ratio (LTV): up to 60%
- Minimum monthly income requirement: IDR 25 million (approx. $1,560)
This development signals growing institutional support for foreign investment in Indonesia’s housing sector.
Instalments as an alternative to mortgages in Indonesia
In Indonesia, developers are offering instalment plans as an alternative to mortgages for foreign buyers. These plans facilitate the de-facto bypassing of ad hoc bureaucratic obstacles, thus creating transparent and favourable conditions for property purchases.
Instalment terms, including interest and payment schedules, are agreed upon individually with developers.
In Indonesia, instalment plans are often interest-free, with payments spread over months or years without additional surcharges and rates.
Common Instalment Plans in Indonesia
Downpayment
During construction
Upon handover
From $145,000
Yield 10.0% Completion in: 2028.I
From $248,000
Yield 9.0% Completion in: 2027.III
From $126,000
Yield 8.0% Completion in: 2027.II
 From $394,000
Yield 12.8% Completion in: 2026.IV
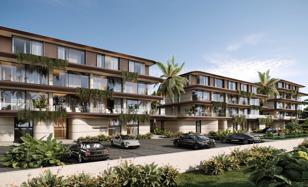 From $176,000
Yield 9.0% Completion in: 2027.IV
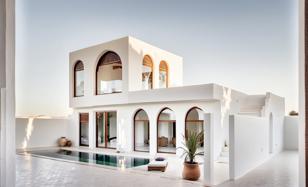 From $120,000
Completion in: 2026.IV 49 units in total
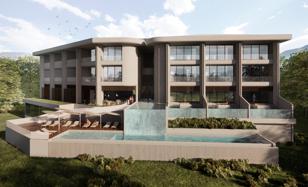 From $440,000
Yield 7.0% Built in 2025
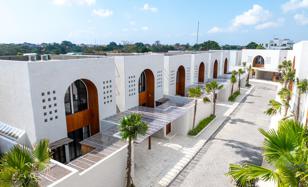 $440,000
Total area 142 m² 3 bedrooms
Property Purchase in Indonesia for Foreigners
The documents depend on the transaction: a leasehold purchase usually requires a valid passport, while Hak Pakai registration and bank financing can also require KITAS or KITAP, proof of income and property documents. See the guide to buying property in Indonesia.
The entire transaction can be completed remotely. Contact our experts to find property in Indonesia online.
Contact us
Once all agreements have been finalised, the investor and developer enter into a contract that outlines each party’s obligations, the property transfer process, and the payment procedure.
It is common for developers to offer management services for the property, which are regulated by a separate agreement if the investor plans to transfer management responsibility.
Once the purchase has been completed and the final instalment has been paid, the sales contract is notarised and the new owner is entered in the local property register as the legal owner for the lease period.
How can you get Mortgage (Instalments) in Indonesia
While mortgage in Indonesia remains limited for foreigners, new programs and flexible instalment plans make it increasingly feasible to invest in real estate, especially in sought-after destinations like Bali. The purchase of property from a developer in instalments starts with the reservation of a property by paying an Expression of Interest (EOI).
Once an expression of interest has been submitted, the purchaser must sign an agreement with the developer. Investors might be willing to provide:
- passport with at least six months of validity;
- сapital for the down payment of 30–50% of the property’s total cost.
Prior to finalising the agreement, investors may request documentation from the developer to verify the legitimacy of its operations. Typical documents provided by the developer include:
- вuilding permit (Persetujuan Bangunan Gedung);
- land title certificate;
- land tax receipt (PBB);
- Indonesian account and tax numbers.
🏦 Home equity loan in your country
🤝 Fractional property investment
📉 Buying off-plan at a discount
We will send you a content digest not more than once a week