Mortgage in Dubai for Non-Residents: Rates in 2026
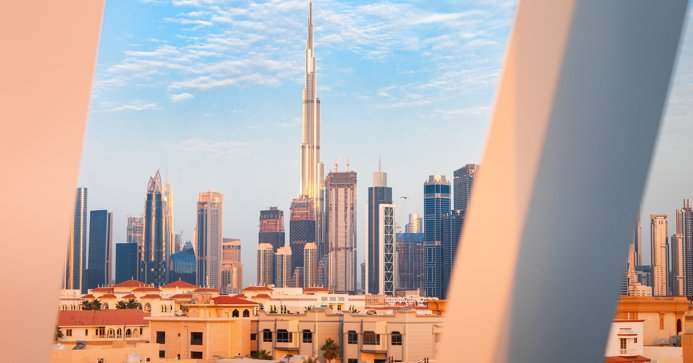
Dubai offers mortgage financing options for international investors, though these are predominantly available for resale properties. Lending criteria vary between UAE nationals and foreign buyers, with non-residents facing more restrictive conditions.
Developers in Dubai also provide instalment payment plans, some of which extend beyond the construction phase, allowing buyers to spread payments over several years after completion.
Mortgage Financing in Dubai: Terms for Residents and Non-Residents
Banks in Dubai extend mortgage facilities to foreign buyers, with different conditions for residents and non-residents. A passport and proof of income are common requirements; an Emirates ID is generally requested from UAE residents, while non-residents may apply under dedicated bank programmes.
The repayment period for property loans in Dubai can extend up to 25 years.
For those obtaining a residency visa, a credit history can be established within six months of issuance.
Total debt obligations — including new and existing loans — should not exceed 50% of the borrower’s monthly income. Additionally, after settling all financial commitments, the remaining income per family member must be at least $950 per month.
According to Mortgage Finder, in 2024, British nationals accounted for 40% of mortgage applicants in Dubai, followed by Indian buyers (30%) and French nationals (9%).
Mortgage Rates in Dubai
As in other global markets, UAE banks offer both fixed-rate and variable-rate mortgage options.
Interest rates start from approximately 4% per annum.
Loan-to-value (LTV) ratio | 50–80% |
Interest rates | from ~4% |
Loan tenure | up to 25 years |
Minimum borrower age | 21 years |
Maximum borrower age | 65 years |
Borrower Requirements in the UAE
- Age between 21 and 65 years.
- Strong credit history.
- Minimum monthly income of $4,084 (as per HSBC and Emirates NBD).
- Proof of legitimate income sources for mortgage repayments.
- UAE residency status may be required.
The UAE’s regulatory framework mandates that borrowers must provide a down payment from their own funds, without relying on additional financing sources.
LTV limits vary based on property value, borrower category, and whether the property is ready or off-plan:
Maximum Loan-to-Value (LTV) Ratios
Property Value | Below AED 5M | Above AED 5M | Off-Plan |
UAE Nationals | Up to 85% | Up to 75% | 50% |
Foreign Buyers | Up to 80% | Up to 70% | 50% |
Source: Central Bank of the UAE
Property Requirements for Mortgage Approval
The Central Bank of the UAE mandates that any mortgaged property must be eligible as collateral, requiring formal registration as a mortgage asset under UAE law, specifically through the Dubai Land Department (DLD).
To qualify for mortgage financing, the property must:
- Hold a clear legal title, free from encumbrances or legal restrictions that could hinder the bank’s ability to enforce collateral rights in case of default.
- Be located in a designated freehold zone.
- Be either completed or scheduled for handover within two years from the mortgage issuance date.
Before approving a mortgage, banks require an independent property appraisal conducted by a qualified third party, unaffiliated with the borrower, seller, or developer. This valuation must reflect the property’s current market value, excluding any assumptions about future price appreciation.
Can One Obtain a UAE Residency Visa with a Mortgaged Property?
Yes, purchasing property with a mortgage in Dubai can qualify an investor for residency visas.
The ten-year Dubai Golden Visa can be available for property purchased for at least AED 2 million (about $545,000). Mortgaged property can qualify if a bank letter confirms that at least AED 2 million has been paid.
Dubai’s ordinary property-investor residence is valid for two years. DLD states no minimum property value for individual ownership; for joint ownership, the applicant’s share must be at least AED 400,000 (about $109,000).
 From $505,000
Completion in: 2029.II Total of 1097 apartments
 From $213,000
Completion in: 2027.IV Total of 210 apartments
 From $738,000
Completion in: 2027.IV 108 units in total
 From $157,000
Completion in: 2028.II Total of 5800 apartments
 From $272,000
Completion in: 2029.II Total of 726 apartments
 From $589,000
Completion in: 2027.IV Total of 291 apartments
What Happens If You Miss a Mortgage Payment in Dubai?
If a mortgage payment is not made on time, the lender has the right to initiate a forced sale of the property through a public auction. However, this process can only begin after the borrower has been formally notified via a notary and given 30 days to settle the outstanding debt.
Should the borrower fail to make the payment within this period, the executing judge — upon the lender’s request — may issue an order to seize and sell the property.
In certain cases, the borrower or guarantor may apply for a delay of up to 60 days to prevent an immediate sale. However, this extension is granted only once and is subject to proof that the debt can be repaid or that an urgent sale would cause significant financial harm.
UAE Banks with Competitive Mortgage Rates

For both UAE nationals and expatriates working in Dubai, mortgage financing remains a key tool for property acquisition. However, rising interest rates in recent years have made borrowing more expensive, particularly impacting demand in the mid-range property segment.
A potential reduction in the UAE’s benchmark interest rate in 2025 could ease mortgage costs, providing an additional stimulus to Dubai’s real estate market.
Not all banks in the UAE provide mortgage financing to non-residents. Below are some of the major, reputable financial institutions offering mortgage options to international buyers:
- HSBC — a leading global bank with operations in the UAE that offers mortgages to foreign buyers earning at least AED 15,000 per month (approx. $4,080). Interest rates start from 4.9%.
- Emirates NBD — the UAE’s second-largest bank that provides mortgage financing to international buyers with interest rates from 4.09%.
Bank & Product | Mortgage | Fixed Rate | LTV |
Up to $5.4 million | From 4.09% | 80% | |
Up to $4.86 million | From 4% | 80% | |
Up to $4.05 million | From 5.10% | 80% | |
Up to $5.4 million | From 4.9% | 60% |
Over the past three to four years, property values have risen by more than 50%, prompting many homeowners to consider refinancing with capital release for home renovations or additional property acquisitions.
Required Documents for Mortgage Application in Dubai
- Copy of passport.
- Copy of residency visa.
- Original and copy of Emirates ID.
- Documents proving financial capability (e.g., recent bank statement for the last six months; salary certificate from employer).
- Proof of legal source of funds.
- Sale agreement for the property.
- Title deed of the property.
- All documents must be translated into English or Arabic.
Mortgage Application Process in Dubai
Step 1: Choosing a Bank
1–2 weeks
The buyer reviews offers from both local and international banks. Once a bank is selected, it conducts an internal assessment to confirm the applicant meets the necessary requirements.
Step 2: Property Selection and Document Submission
2–6 weeks
After receiving bank approval, the buyer has up to two months to choose a property. Once selected and reserved, the buyer signs the sale agreement, registers the transaction with the Dubai Land Department (DLD), and receives the title deed, which is then submitted to the bank.
Step 3: Signing the Mortgage Agreement
1 day
The borrower meets with the bank to discuss the terms of the mortgage and signs the agreement.
Step 4: Making the Initial Payment
1 day
The borrower makes the required down payment. It’s also recommended to secure property insurance at this stage.
Afterwards, the borrower continues making regular mortgage payments according to the agreed schedule.
Frequently Asked Questions (FAQ)
Even non-residents can apply for a loan in the UAE. To do so, simply visit the chosen bank with the required documents. At a minimum, you will need a passport copy and bank statement. If available, a residency visa and Emirates ID may also be required.
Mortgages are available only for properties located in freehold zones of Dubai. These areas include popular districts such as Dubai Marina, Downtown Dubai, some districts of Jumeirah, and many more.
The down payment size, borrower’s financial stability, credit history, residency status, and the bank and mortgage product selected all play a role in determining the interest rate and monthly payment amounts.
We will send you a content digest not more than once a week